In boardrooms and executive meetings, financial health is usually discussed through isolated key performance indicators:
Debt-to-Equity: Evaluated to judge solvency and risk tolerance.
Operating Cash Flow: Monitored to gauge day-to-day liquidity.
Profitability & EBITDA: Tracked to measure commercial growth and operational scale.
While tracking these metrics individually is standard practice, looking at them in isolation creates a dangerous financial blind spot.
Most traditional risk models view a rising Debt-to-Equity ratio as the primary source of financial danger. However, experienced financial leaders know a fundamental truth: Debt is rarely the root cause of financial distress—it is almost always the symptom.
The Domino Effect: From Cash Flow to Balance Sheet Pressure
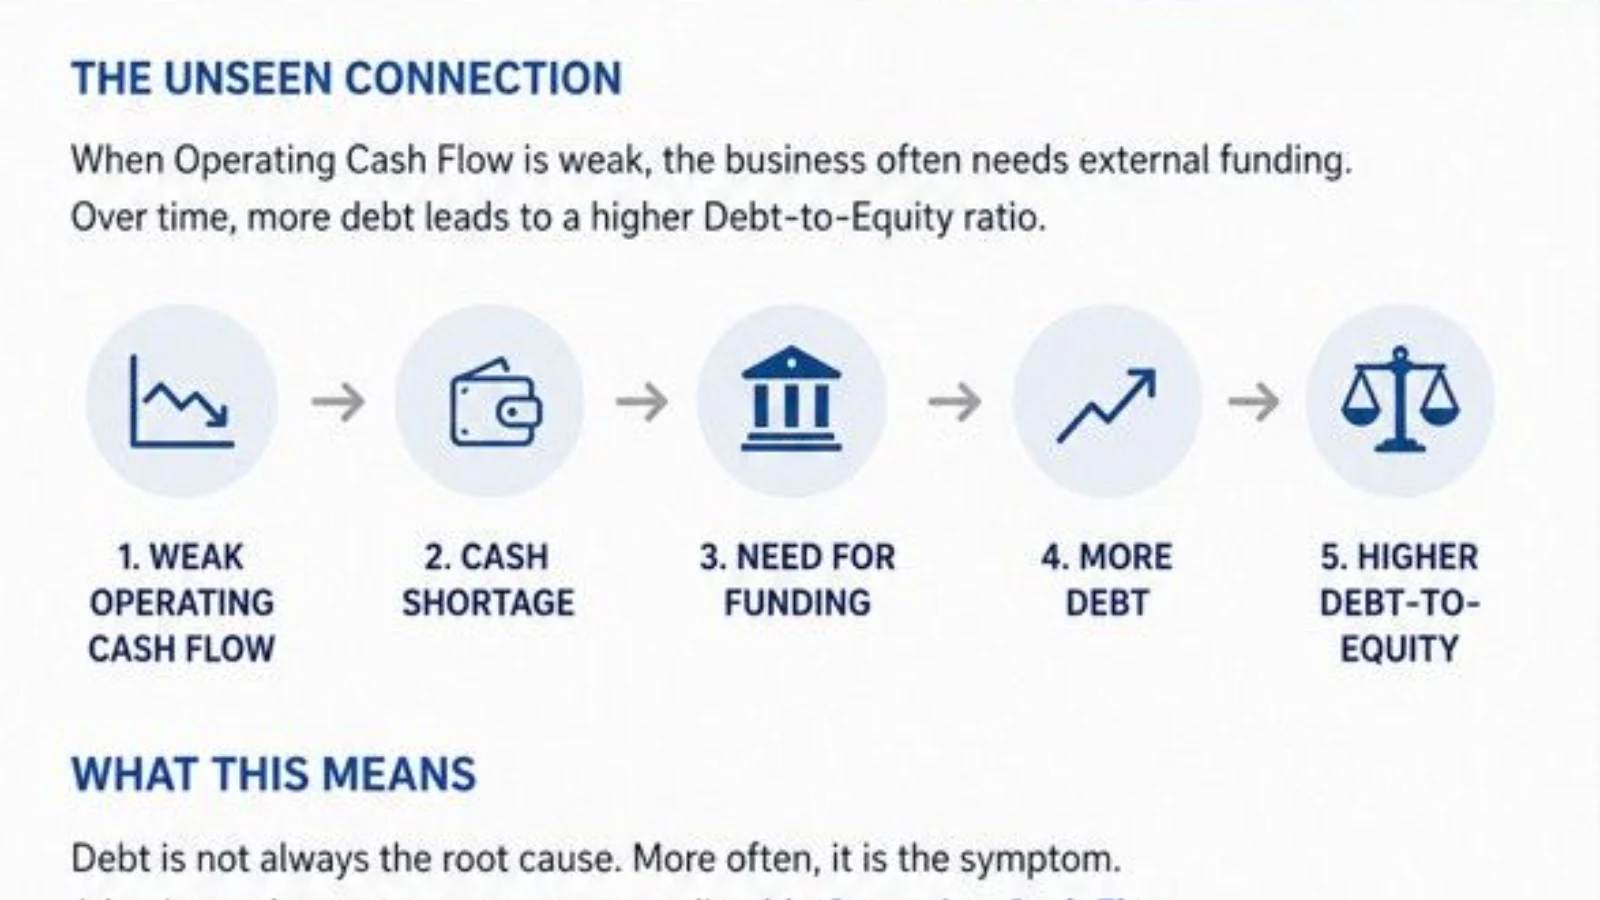
To understand why leverage increases, you have to look at what happened long before the debt was taken on. The chain reaction begins with Operating Cash Flow (OCF).
When a company consistently generates strong, predictable Operating Cash Flow, it achieves self-sustainability. It can fund daily operations, re-invest in capital expenditures, pay dividends, and service existing obligations entirely from organic cash generation.
When Operating Cash Flow weakens—whether due to margin compression, slow collections, overstocking, or declining sales—the business faces an immediate liquidity gap. Management is left with only a few options to keep the business running:
Borrow more money (short-term loans, revolving credit lines, or long-term bonds)
Raise equity capital (often dilutive and slow to execute)
Sell off core or non-core assets
Implement aggressive cost-cutting measures
In most operational environments, borrowing money is the fastest, least disruptive fix. Over time, as weak cash flow persists, the company relies on continuous debt to bridge the gap.
Eventually, this accumulated debt shifts the balance sheet structure—pushing the Debt-to-Equity ratio higher.
Weak Operating Cash Flow today becomes high Debt-to-Equity tomorrow.
Rethinking Risk: Context Over Metrics
Because leverage is the lagging indicator of a cash flow problem, looking at Debt-to-Equity without cash flow context leads to flawed strategic decisions.
Consider two contrasting corporate profiles:
Company A: Has a Debt-to-Equity ratio of 2.0, but generates robust, recurring, and highly predictable Operating Cash Flow.
Company B: Has a conservative Debt-to-Equity ratio of 0.5, but suffers from volatile, negative, or deteriorating Operating Cash Flow.
At first glance, traditional financial screens might flag Company A as high-risk due to its leverage. In reality, Company A's strong cash generation allows it to easily service interest obligations, pay down principal, and navigate economic downturns.
Company B, despite its low balance-sheet leverage, is on a dangerous trajectory. Without organic cash generation, its cash reserves will drain, forcing it to either take on heavy debt at unfavorable terms or face an operational crisis.
The Reality of Debt Repayment
EBITDA looks clean on an executive summary, revenue shows commercial reach, and net profit flatters the income statement. But when debt covenants mature and interest payments come due, none of those metrics settle the bill.
Debt is repaid with cash—not with accounting profits, valuation multiples, or pitch decks.
For CFOs, finance leaders, and business intelligence teams, the takeaway is clear: stop analyzing financial ratios in silos. By connecting P&L performance and balance-sheet leverage directly back to underlying cash flow dynamics, leaders can identify operational vulnerabilities early—fixing the cash generation engine long before debt becomes a crisis.
Tags
#Finance #CFO #BusinessIntelligence #DataAnalytics #CashFlow #Leadership #FinancialReporting #CorporateFinance