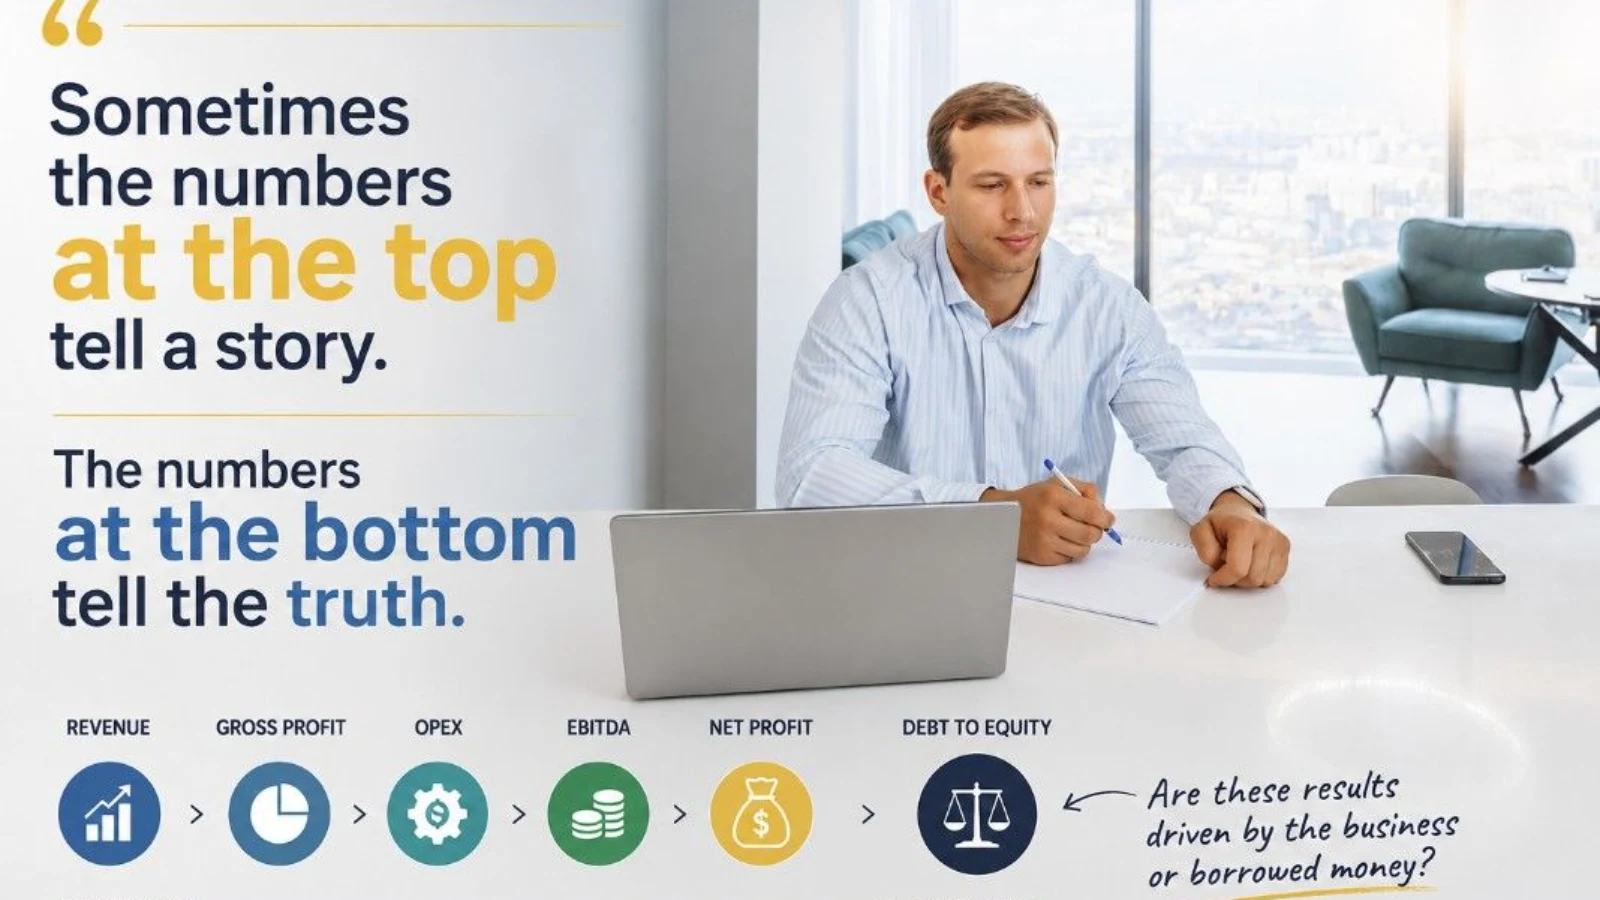
When building executive dashboards and board reporting packages, standard practice follows a familiar hierarchy down the Profit & Loss (P&L) statement:
Revenue – Measures top-line demand and commercial reach.
Gross Profit – Evaluates core product economics and pricing strategy.
Operating Expenses (OpEx) – Highlights overhead efficiency and administrative scale.
EBITDA – Assesses baseline operational earnings power before non-cash accounting adjustments.
Net Profit – Captures the final bottom line after interest, taxes, and depreciation.
Each of these metrics tells a valuable chapter of the operational narrative. Revenue shows market traction, gross margins reflect competitive advantage, and EBITDA indicates cash-generation potential from daily operations.
However, relying solely on P&L performance creates a critical blind spot. An income statement measures activity over a defined timeframe—a month, quarter, or year—but tells you very little about long-term solvency or underlying risk.
To understand whether growth is sustainable or fragile, leaders must look past the profit metrics and examine the balance sheet, where one key indicator sits: the Debt-to-Equity (D/E) ratio.
Understanding the Debt-to-Equity Ratio
The Debt-to-Equity ratio compares a company’s total financial liabilities to the equity invested by its shareholders:
While P&L numbers measure how much money flows through the business, the D/E ratio measures how the business itself is funded. It answers a fundamental strategic question:
Are these profits being generated by operational excellence, or are they being propped up by borrowed money?
The Mirage of High Leverage
Financial leverage acts as a force multiplier. In a bull market or during periods of low interest rates, high leverage can make operational performance look extraordinary:
Amplified Returns: Borrowed capital allows a company to fund acquisitions, expand sales teams, and build infrastructure faster than organic cash flow allows.
Flattered Margins: Top-line growth masks the hidden liability accumulating on the balance sheet.
However, leverage works in both directions. When market dynamics shift, demand cools, or interest rates rise, a company with high debt-to-equity faces compounding risks:
Fixed Debt Obligations: Unlike variable operating costs, debt servicing costs (principal and interest) remain constant regardless of revenue drops.
Erosion of Free Cash Flow: High debt loads consume operational cash flow just to service interest, leaving zero capital for reinvestment, innovation, or unexpected downturns.
Refinancing Risk: Expiring debt must often be refinanced at significantly higher interest rates, suddenly turning a "profitable" operational model into a net-loss enterprise.
Two companies can report identical revenue growth, identical gross margins, and identical net profits. Yet, the company funded entirely through retained earnings holds immense strategic flexibility, while the company funded through heavy leverage carries existential risk.
Financial Acceleration vs. Long-Term Obligation
Using debt is not inherently flawed. Debt is often the most cost-effective way to lower a company's Weighted Average Cost of Capital (WACC) without diluting existing equity holders. Strategic leaders use debt selectively to:
Fund High-ROI Capital Expenditures (CapEx) with predictable payback periods.
Bridge Working Capital Gaps during periods of hyper-growth.
Execute Strategic M&A that adds immediate, accretive value.
The crucial responsibility of financial analysts and data leaders is separating operational performance from financial engineering. The goal of executive analytics is not just to report profit, but to clarify how much of today's commercial success is genuinely organic—and how much is borrowed against tomorrow's performance.
The CFO Perspective: P&L vs. Balance Sheet
As data analytics and business intelligence evolve from descriptive reporting toward executive decision science, a fundamental rule emerges:
The P&L measures operational activity.
The Balance Sheet measures structural stability.
Top-line revenues and profit margins show how fast the vehicle is moving. The balance sheet shows whether the engine can sustain the speed without running out of fuel.
By integrating balance sheet metrics like Debt-to-Equity directly alongside P&L performance indicators in executive reporting, analytics teams provide leaders with complete context—ensuring growth is built on solid ground rather than borrowed time.
Tags
#Finance #DataAnalytics #BusinessIntelligence #CFO #FinancialReporting #DebtToEquity #BusinessPerformance #DataLeadership